Agentic Problems and Forces Creating Alignment

In June I wrote Agentic Apocalypse: How to Stop It. That blog was about intent: agents buying the wrong thing, and platforms grading their own homework. Intent is a real problem. It is not the biggest one. The larger problem is the economic model of agentic, which I first framed in Pricing Agentic: Economic Models for a New Kind of Demand and called the Gordian Knot in Agentic Commerce: I’ve Seen a Lot of Revolutions. This One Feels Different.

Today’s blog takes eight questions in turn. The short version: agentic activity is real and growing, agents still get it wrong too often, and nobody has priced the value they create. Merchants pay for everything in commerce, payments and advertising. Any model, agent or platform ignoring this dynamic will fail. Today’s focus is identifying forces that will create alignment (and they favor the card networks).

Continue reading →
How Will Stripe Treasury and Balance Impact SMB Banks?

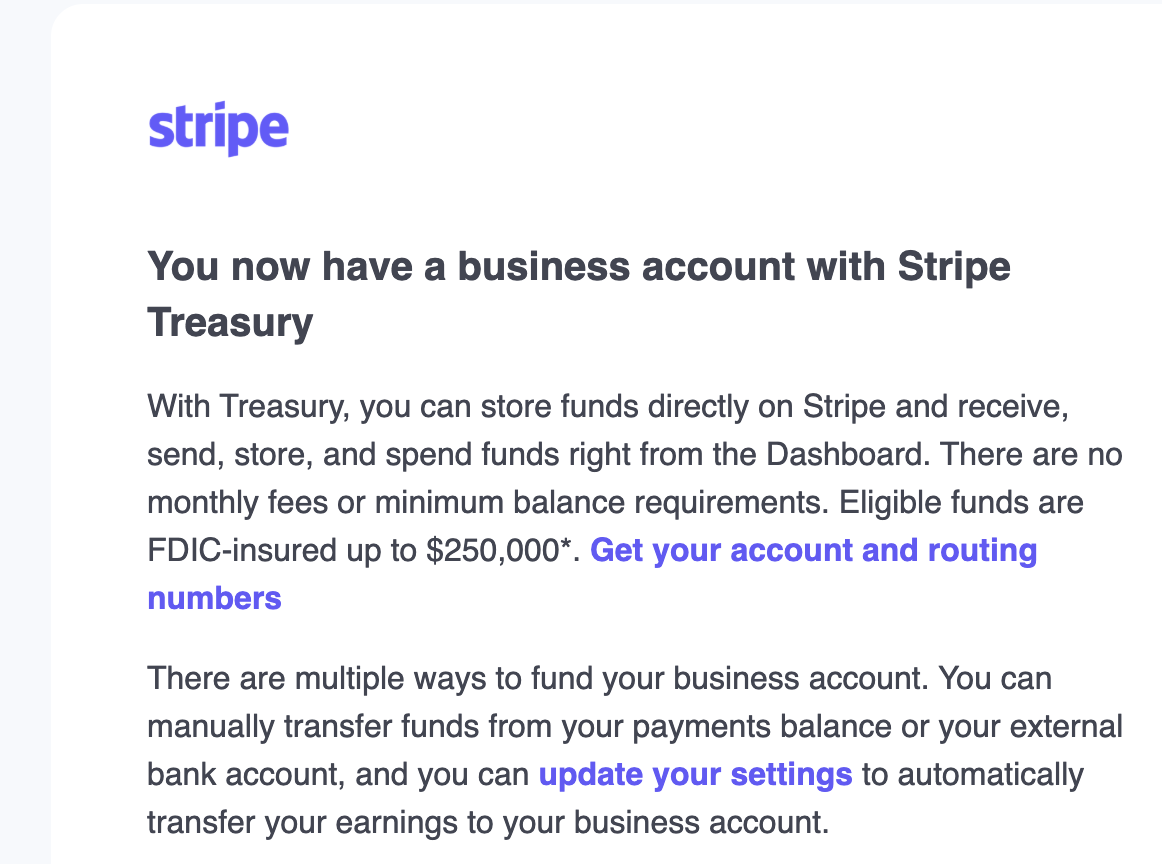
I am a loyal Bank of America customer (personal and business); I have absolutely no interest in changing banks given their 20+ year history of consistent service. I’m also a Stripe customer (blog payments) and am fantastically satisfied with their payment processing. Yesterday I received this email from Stripe.

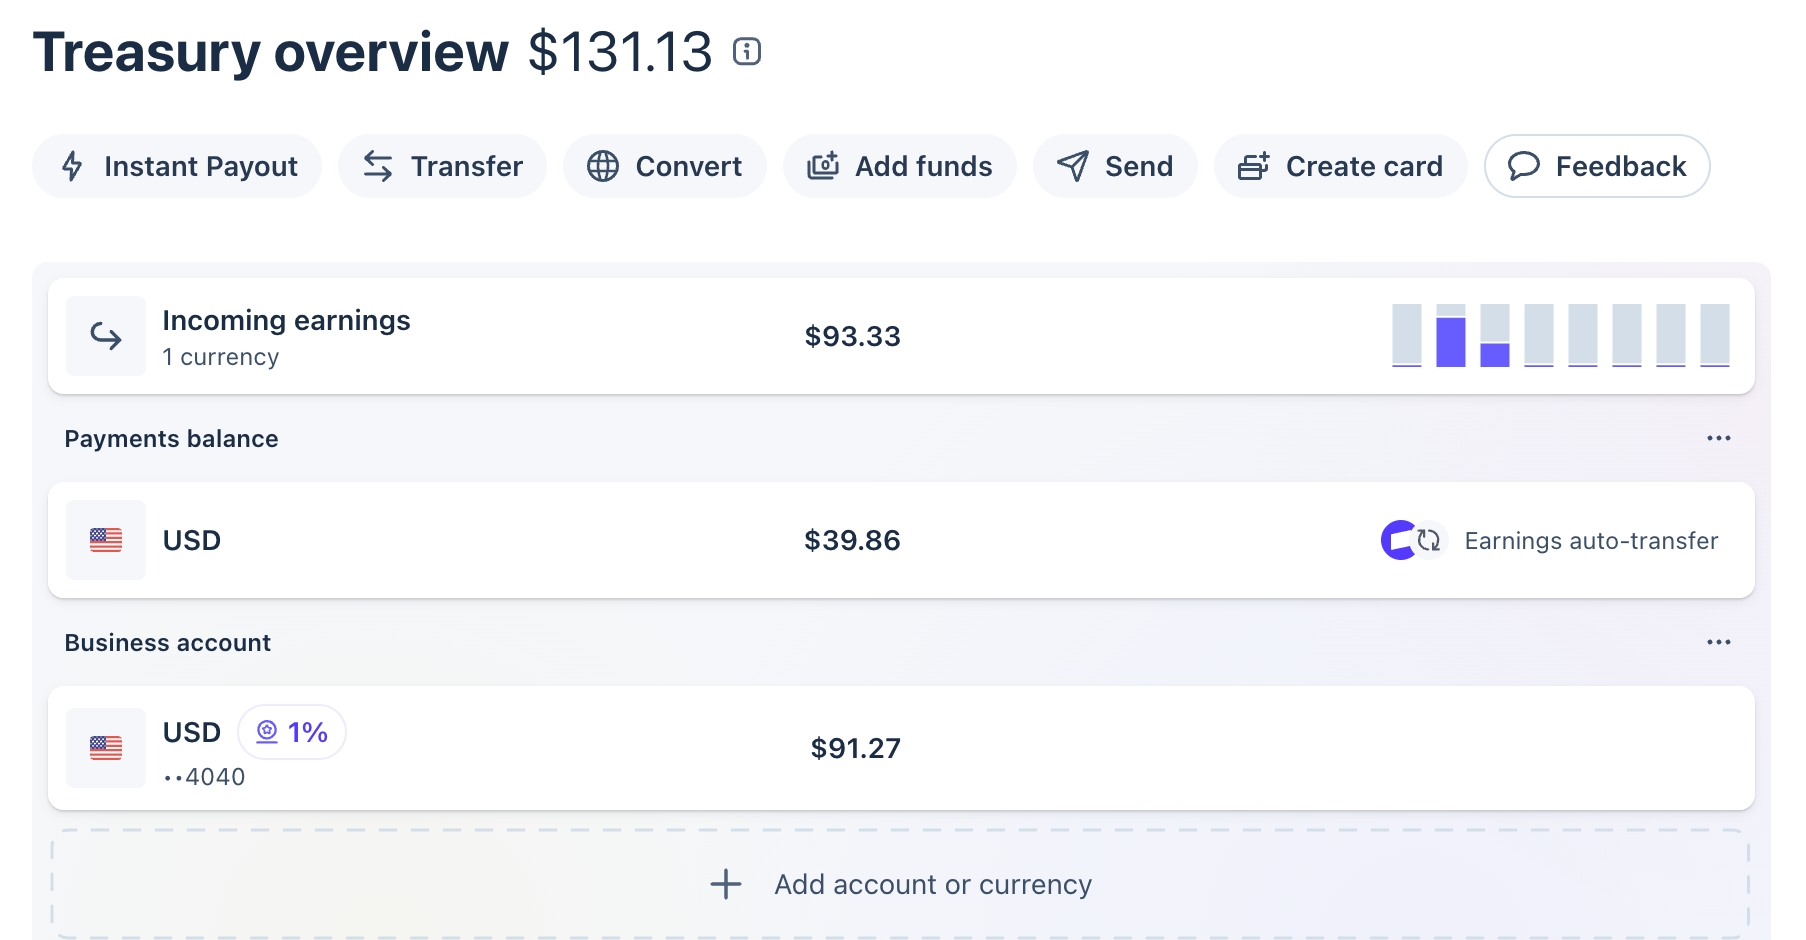
I’m now enabled for Stripe Treasury. With a single button click I can now move money in real time anywhere in the world for $0 cost and earn 1% on my balance. 

This is an amazing value proposition. My 15 seconds of effort to turn this on led me to think about the impact of Treasury and Balance on SMB banks. Feedback appreciated.

Continue reading →

Shopify Reduces Stripe Dependency

This week Shopify released its Fall ’26 Edition content. The payments news is that Shop Pay now works inside personal agents (Muse, Claude Duet, Grok Bot and Instinct), and it works for brands that are not on Shopify. I found a great tech overview of the payment portion in Shopify Takes Shop Pay Into AI Agents and Off Platform Checkouts (The Defiant, Oct 29, 2026).

I am positive on Shopify as the best agentic enabler for merchants. ShopPay is also the best converting consumer wallet in eCommerce. Edition outlines how ShopPay competes directly with Stripe Link, at the moment Stripe is seeking to expand its consumer role within agent permissioning (see last week’s blog Stripe Link Balance). Stripe and Shopify have been partners for more than a decade. Payments is now a core area of friction.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Stripe Link Balance

This week Stripe launched Link balance for AI agents, starting with Instinct (Announced on X by Stripe). Stripe balance is the “agent control dashboard” where Consumers add money, set a per purchase limit, and their agent can buy without asking for approval every time. Read it. On the surface it is a wallet feature. Underneath it is Stripe building a consumer business, because right now Stripe is the only company that can make agentic payments work.

I think this is brilliant, but Issuing banks, merchants, MSPs and other agentic Platforms should take note of Stripe’s very big expansion into consumer direct interaction

What Stripe Launched

The stack has four parts

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Meta’s Muse: The Agent Becomes the Control Point

Three weeks ago I argued that Meta would stay upstream as a preference and affinity layer and leave checkout to retailers. Half of that held. Meta is not taking checkout from retailers. But Muse is more than a preference layer. It is an attempt to build a new orchestration point, one that sits between the consumer, the merchant, the wallet, and the payment network.

The shift I am watching is from wallet-centric commerce, where the merchant owns the interaction and presents payment choices, to agent-centric commerce, where the agent orchestrates merchant, wallet, credential, and transaction. If that shift happens at scale, Visa, Mastercard, Stripe, PayPal, banks, and wallets become services the agent can use. Meta owns the consumer relationship and the purchase intent, which is worth more.

Continue reading →

PayPal – Stripe/Advent: Whose Deal Is This?

As a reminder, I’m not a financial analyst, more of a payment historian, operator and P&L exec. This is my third pass at the Stripe/Advent bid for PayPal. The first was reporting on the Reuters story. The second was opinion, built around three concerns: merchant pricing, enterprise access, and consumer engagement. Something changed since then, and it did not come from the deal. It came from Stripe.

This week Stripe confirmed its acquisition of OpenRouter for more than $7 billion, and the Collisons published a letter to investors talking about “the singularity” and the economics of AI token flow. OpenRouter has nothing to do with PayPal. That is precisely why it matters. Read the letter alongside Stripe’s annual letter from February and you get an unusually clear statement of where this company thinks its growth comes from. PayPal is not in that statement. Not adjacent to it. Not implied by it. Absent.

Thus this blog represents my internal dialog as I ask myself: whose deal is this? My answer: this is Advent’s deal. Stripe is in the room for one or two assets, and the structure of the bid is starting to show it.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Stripe/Advent – PayPal: My Thoughts

Two weeks ago I wrote up the Reuters report that Stripe and Advent had offered $53B for PayPal. That post was mostly reporting, plus some structural background on operating models and processing volumes. This one is opinion. You have been warned.

Let me start with the disclaimer that matters. I am not a financial analyst. I have no idea whether paying roughly 7x PayPal’s ~$8B in EBIT is a bargain or bizare. Kenneth Suchoski at Autonomous Research put the implied multiple at about 11x 2027 NOPAT and called the financing “a lot of debt to put on this asset,” which sounds about right to me, but he does this for a living and I do not.

What I do know something about is payment networks, merchant behavior, and consumer adoption. On those three dimensions I have 3 concerns:

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Stripe/Advent offer $53B to buy PayPal

Sometimes the biggest signal is not the price, it is who is showing up with the money. This morning, Reuters reported that Stripe and Advent International have jointly offered to acquire PayPal for more than $53 billion. Stripe, the largest privately held payments company on the planet, has walked into the room and said, in effect, we would like to own the incumbent. That framing alone reorganizes how you should read the last five years of PayPal’s decline and the next five years of network competition.

I have been writing about PayPal’s structural problems for a long time. Most recently in PayPal, Alex is Gone, Enrique is In. Recommended Focus, where I argued that Enrique Lores was inheriting a “dumpster fire” of acquisitions and shifting consumer focus, and that the only path forward was decisive surgery on the operating model. A $53B “take private” from Stripe and Advent is one very specific answer to that question. Today’s blog is a quick overview of the Reuters report together with my own read, and questions any investor should be asking before they get out over their skis on this.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Open USD – Stablecoin’s New Gold Standard for Trust, Compliance, Governance and Economics

July 1, 2026

Executive Summary

  • 140+ institutions — Visa, Mastercard, Stripe, BlackRock, Google, Coinbase, and major global banks form the largest stablecoin consortium ever assembled
  • Shares reserve economics — Partners receive yield from underlying reserves, not the issuer; flips the Circle/Tether model
  • Zero-fee minting at scale — No volume limits, no enterprise penalties
  • Pre-transaction compliance — Transfer hooks block sanctioned transactions before settlement, not after
  • Burn and clawback authority — Architectural ability to freeze/burn for OFAC compliance built into Token-2022 implementation
  • Confidential transfers with regulatory visibility — ZK-encrypted balances for corporate privacy; viewing keys for auditors
  • Neutral governance — Independent board of ecosystem partners; no single corporate controller
  • Stripe default — “The default stablecoin for businesses running on Stripe”

Yesterday, we witnessed the launch of what may become the most consequential stablecoin ever: Open USD (OUSD). With over 140 financial, technology, and crypto institutions signing on—from Visa and Mastercard to Stripe, BlackRock, and Google. This isn’t merely another stablecoin entering a crowded market. This is the emergence of a new trust network architecture that I’ve been writing about for years.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Explaining the Death of OpenAI’s Instant Checkout

Short Blog

To my regular readers, you know the flow of data within a network is complex (see Data Games). The news that OpenAI is effectively shelving its “Instant Checkout” initiative in favor of a referral-based “conversational commerce” model shouldn’t come as a surprise. While the tech press might frame this as a strategic pivot, those of us in the eCommerce trenches know it for what it is: a collision with merchant’s role in risk, costs, CX, control and their own AI dreams.

OpenAI attempted to solve its monetization problem by trying to seize control of the top of the funnel, betting that the sheer volume of consumer demand would force merchants to bow to their interface. They were wrong. They fundamentally miscalculated the power dynamics of the transaction and the complexity of the global conversion funnel, a funnel that Google understands intimately because they serve both ends of it globally (ie merchant partners).

Continue reading →