Agent Collaboration: CX Advantages of Muse and Instinct

Short blog. The economic model of agentic commerce is not settled. I framed the problem in Pricing Agentic: Economic Models for a New Kind of Demand, returned to it in Agentic Problems and Forces Creating Alignment, and noted in Agentic Reality: Advertising that the first working business model is ads, not checkout. Nobody has priced the value an agent creates. Merchants still pay for everything. Two models are now competing to answer that question.

Control vs. Collaboration

Platforms want end-to-end control. Their agentic strategy protects ad revenue. Amazon blocked Muse within two weeks of launch (Meta’s Muse), and eBay followed. Google shipped Gemini Tasks, AP2 and Wallet on iOS in one day (Google’s Big Day). The goal is a great experience inside the Gemini domain.

Personal agents are building a different model: agent-to-agent collaboration. Muse and Instinct do not need to own the merchant’s checkout, “all” data or customer. They need to own the consumer’s intent and “buyer data” and hand it to specialized “seller” agents that can act on it.

Muse + Sparky

Muse and Walmart are about to launch the first agent-to-agent commerce integration. Muse uses Walmart’s MCP for products, carts and orders, and talks to Sparky, Walmart’s agent, for orders, stores, policies and comparisons. My take on X: this is how specialized agents should work.
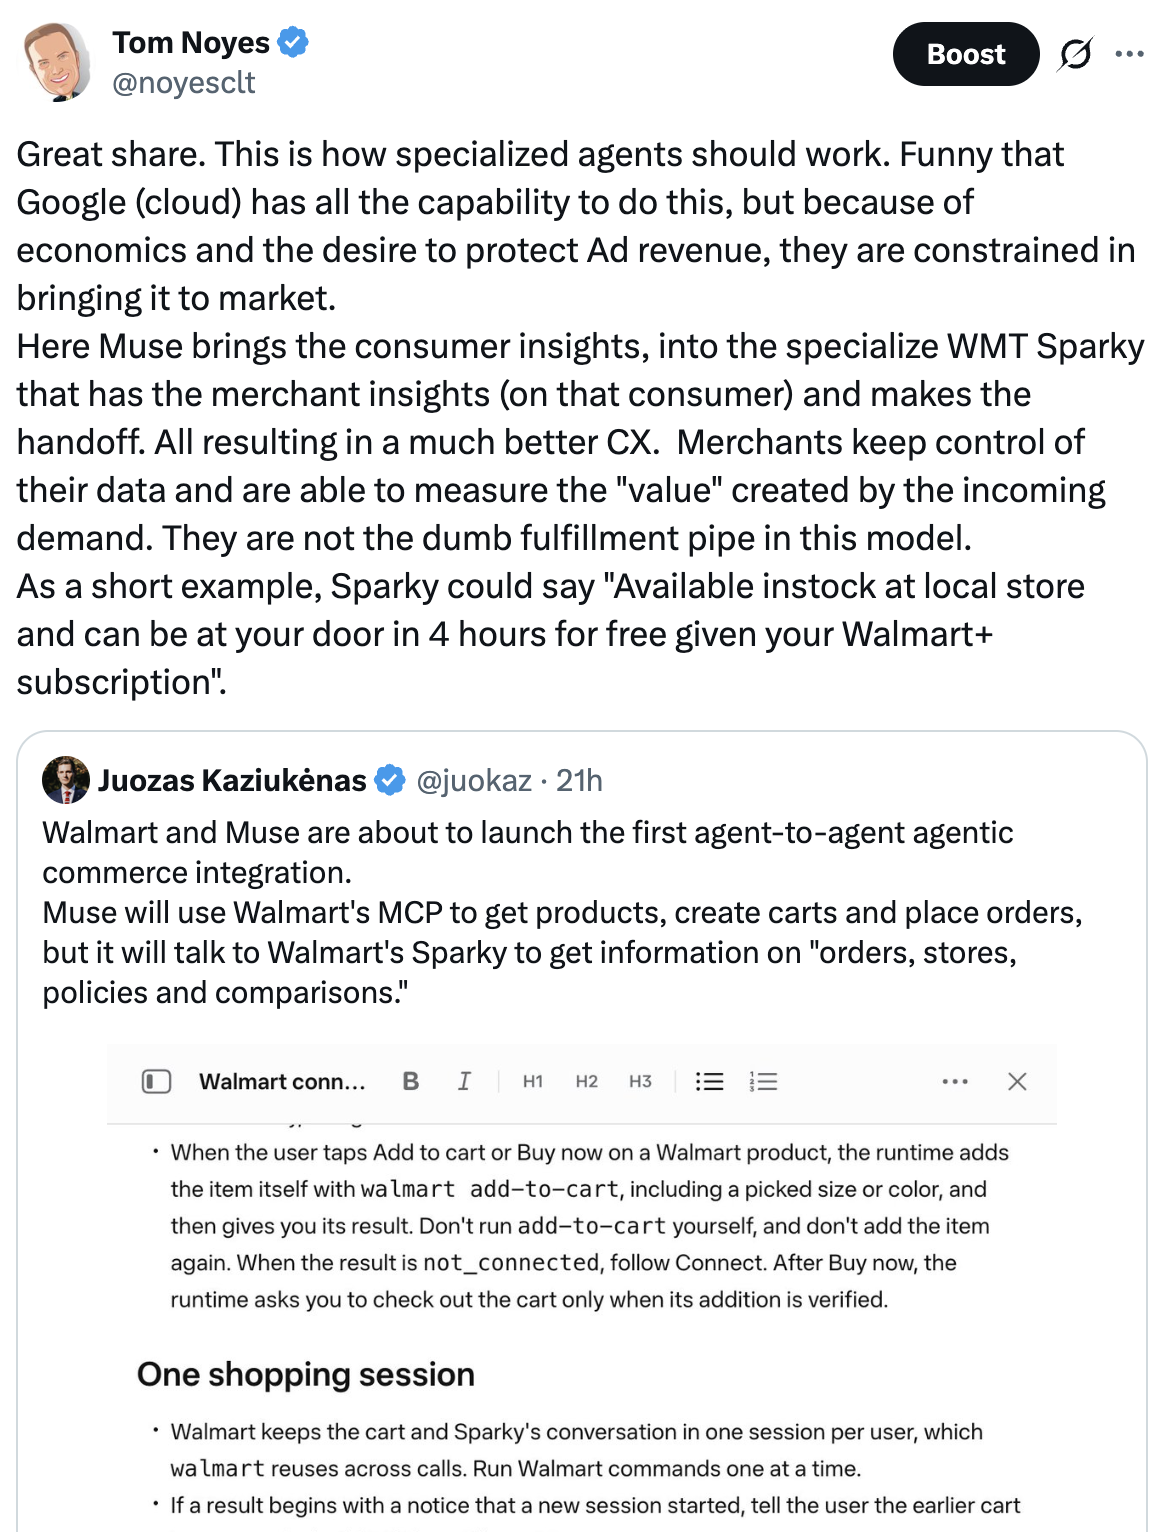
  • Muse keeps the consumer intent. It knows you anbd what you want, across every merchant “buyer agent”
  • Sparky is specialist “seller agent”. It knows what Walmart knows about you: Walmart+ status, local inventory, order history. It does not share that insight with Muse. This is the design I described in Walmart Agent Gateway: agents find your usual items without Walmart handing over purchase history.

Sparky’s answer is one Muse cannot produce alone: in stock at your local store, at your door in 4 hours, free with your Walmart+ subscription.

Who Wins

  • Consumer: a better answer and better value. Local inventory, delivery time and membership benefits enter the decision.
  • Merchant: keeps its data and its checkout. Walmart is not a dumb fulfillment pipe. Because it owns checkout, it can measure the value of incoming demand.
  • Muse: better CX without carrying anyone’s proprietary data. That makes Muse the partner of choice. Merchants have no reason to block an agent that brings demand and takes nothing.

Note that Walmart may not get the sale; Muse will collaborate with many seller agents and pick what is right for the consumer. That is the point.

The Missing Piece is Measurement and Settlement. I’m not talking about payment rail, but rather the commercial construct for measuring and settling value between agents. The merchant can measure value because it owns checkout. Everyone else is blind. Muse cannot see margin. A travel agent cannot see the loyalty uplift it generated for an airline. Without measurement there is no pricing, and without pricing there is no durable economic model. Bilateral side deals (Muse-to-Walmart, Muse-to-Target) do not scale.

This is the role I see card networks filling. They can define standardized commercial settlement constructs based on:

  • merchant category
  • who owns the risk
  • basket on entry vs. total purchase
  • margin
  • loyalty and repeat purchase

The constructs can be many and support multilateral agreements: any buyer’s agent, any seller’s agent, one set of rules. Networks have done this before with interchange. They also own the other piece buyer and seller agents need from an intermediary: identity and authentication. A seller’s agent must know the buyer’s agent is acting within what the consumer permissioned. I made the same case in Agentic Governance: “Standards” are worthless without a Commercial Construct. Someone has to be the cop.

Barriers to Entry

Muse-Sparky collaboration creates a moat. Every specialist agent that joins makes Muse more useful: travel agents that hold your travel preferences, grocery, healthcare, hiking, fitness. Muse wants the best customer experience regardless of whose domain or model sits on the other side.

Google Cloud can build all of this today, but it would significantly impair Google Ads plans. A Gemini that hands your intent to a merchant’s agent, and lets the merchant keep the data, undercuts the ad model.

Google Wallet as Identity Hub? Challenged when you also compete for both consumer and merchant agent role.

In this lens, Google Wallet holding all of your identity credentials looks silly. Which agentic platform or personal agent wants Google tracking your activity across every agent? While DPCs are bearer credentials that do not provide credential issuers with visibility on use, they certainly enable the credential store to track usage. Apple, yes: its business does not run on ads. Banks, yes: they already hold the KYC and the liability. Google? No way.

The buyer’s agent needs a neutral intermediary. The ad company is not neutral.

Bottom Line

The platforms are building walls to protect ads. Personal agents are building handoffs. Handoffs produce better CX, give merchants control and measurement, and make the personal agent the partner of choice. The missing layer is multilateral measurement, settlement and identity between buyer and seller agents. That is the networks’ job to take.
Google AP2 and UCP Market Progress

This is a follow-up to this week’s Google’s Big Day: Gemini Tasks, AP2 and Wallet on iOS. Several readers asked the obvious next question: how does the announcement impact Agent Payments Protocol (AP2) and the Universal Commerce Protocol (UCP)? What of my previous coverage has changed? The biggest questions are commercial. Who owns checkout? Who sees intent? Who takes the risk, and who authorizes the agent? Today I’ll attempt to look for evidence of actual implementations, then answer those questions.

My position has not changed. Google’s engineering is the best in agentic commerce. Its partnership record is the weakest of the large platforms. Standards are how Google creates control and solves problems inside its own domain. A standard cannot solve monetization, risk, or authentication/ authorization for the benefit of a relying party. Those are commercial problems. Note: Thanks to Claude Opus for helping me find relevant references to fact-check today’s post.

Continue reading →

Google’s Big Day: Gemini Tasks, AP2 and Wallet on iOS

Yesterday Google shipped a set of product releases that span agents, AI, payments and a new platform. Tasks in Gemini is now free for hundreds of millions of people in the US, Japan, Korea, Canada, Australia and India. Gemini now pays through the Agent Payments Protocol (AP2) on Visa and Mastercard network tokens, with American Express coming soon. And Google Wallet is now on iOS in the US, positioned as “a secure hub for managing agentic purchases across Google” (Google, Nov 17, 2026).

This is tremendous work from a tremendous team. Google is a bit later than Meta’s Muse to a consumer agent at scale, but it holds advantages no one else can match: roughly 7 billion surfaces, and consumer data from Gmail, Calendar, Maps, Photos, Chrome, Password Manager and Wallet, already in one place. Google says it directly: if your data “already lives at Google securely… you don’t have to send it elsewhere” (Google, Nov 17, 2026).

In evaluating the scale of this release, my questions are not about the engineering, but rather the parts of agentic commerce that engineering alone does not solve: partnerships, control, pricing, intent, permissioning, and pricing.

Continue reading →

ChatGPT Wallet: A Cloud Wallet on Network Rails

OpenAI launched ChatGPT Walle yesterday and it appears to be a new “wallet model” build on card network agentic VAS (V, MA, AMEX). Agents pay with a network token instead of the card number, and the consumer authorizes each purchase within the OpenAI app. It is live for pro accounts inside dots today (US). Dots is OpenAI’s answer to Muse (Meta’s Muse: The Agent Becomes the Control Point). Launched September 29, Dots are a new class of autonomous agents built into ChatGPT. Unlike a normal ChatGPT conversation, a dot has its own cloud computer, persistent context, and access to the applications you authorize. Wallet is how a dot pays.

This is OpenAI’s second go round in checkout (see Explaining the Death of OpenAI’s Instant Checkout). in round 1, OpenAI tried to take the top of the funnel and the checkout, and merchants said no. ChatGPT Wallet is the opposite bet. The merchant stays merchant of record. The card keeps its rewards and dispute rights. The issuer makes the authorization decision. The token goes into the merchant’s existing checkout form. OpenAI has stopped trying to replace the payments plumbing and is now building on the networks’ plumbing.

Continue reading →

European Payments: Android Metaphor

Over the last month, I was fortunate to interview EU banks and non-card payment schemes. The people are just fantastic, and I came away with a new appreciation of the challenges of working in a payments environment with so much “central planning”. The questions I asked myself: How best to achieve the objective of being a “digital first” economy? Centrally planned mandates? or markets with commercial incentives? When there is no margin in payments who can invest in the infrastructure (or governance)?

Europe’s payment ecosystem is shaped by the “central planning” of the ECB and the European Commission: SEPA, PSD2, PSD3 and the Payment Services Regulation (PSR), eIDAS, the Instant Payments Regulation, the digital euro and the EU Digital Identity (EUDI) wallet. I have written about this before, in Payments Innovation in Europe (2011), Building Networks and “Openness” (2011), Open Banking, Open Payments and Trust Networks (2020) and Europe’s Siege (2025). Today’s blog is focused on my new insight: how much of the cost lands on the banks, and how little room that leaves for anything else.

Thought for the day: Mandates build rails. Markets build businesses.

Continue reading →

Agentic Problems and Forces Creating Alignment

In June I wrote Agentic Apocalypse: How to Stop It. That blog was about intent: agents buying the wrong thing, and platforms grading their own homework. Intent is a real problem. It is not the biggest one. The larger problem is the economic model of agentic, which I first framed in Pricing Agentic: Economic Models for a New Kind of Demand and called the Gordian Knot in Agentic Commerce: I’ve Seen a Lot of Revolutions. This One Feels Different.

Today’s blog takes eight questions in turn. The short version: agentic activity is real and growing, agents still get it wrong too often, and nobody has priced the value they create. Merchants pay for everything in commerce, payments and advertising. Any model, agent or platform ignoring this dynamic will fail. Today’s focus is identifying forces that will create alignment (and they favor the card networks).

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

How Will Stripe Treasury and Balance Impact SMB Banks?

I am a loyal Bank of America customer (personal and business); I have absolutely no interest in changing banks given their 20+ year history of consistent service. I’m also a Stripe customer (blog payments) and am fantastically satisfied with their payment processing. Yesterday I received this email from Stripe.

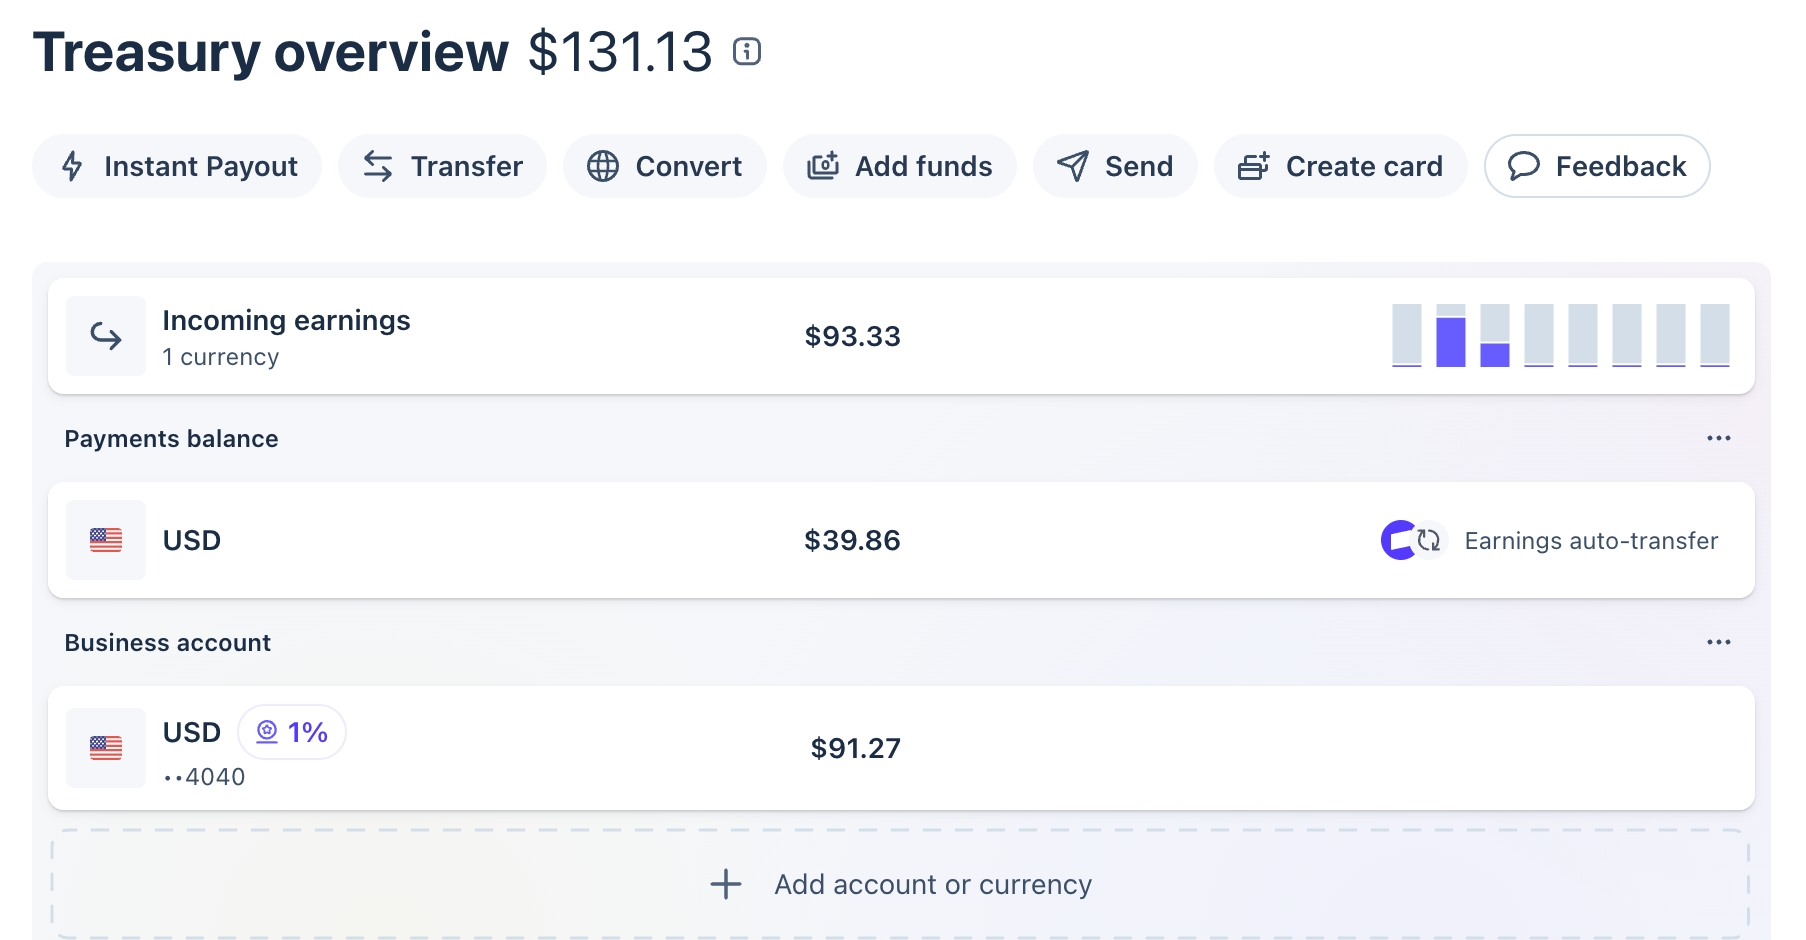
I’m now enabled for Stripe Treasury. With a single button click I can now move money in real time anywhere in the world for $0 cost and earn 1% on my balance. 

This is an amazing value proposition. My 15 seconds of effort to turn this on led me to think about the impact of Treasury and Balance on SMB banks. Feedback appreciated.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Shopify Reduces Stripe Dependency

This week Shopify released its Fall ’26 Edition content. The payments news is that Shop Pay now works inside personal agents (Muse, Claude Duet, Grok Bot and Instinct), and it works for brands that are not on Shopify. I found a great tech overview of the payment portion in Shopify Takes Shop Pay Into AI Agents and Off Platform Checkouts (The Defiant, Oct 29, 2026).

I am positive on Shopify as the best agentic enabler for merchants. ShopPay is also the best converting consumer wallet in eCommerce. Edition outlines how ShopPay competes directly with Stripe Link, at the moment Stripe is seeking to expand its consumer role within agent permissioning (see last week’s blog Stripe Link Balance). Stripe and Shopify have been partners for more than a decade. Payments is now a core area of friction.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Stripe Link Balance

This week Stripe launched Link balance for AI agents, starting with Instinct (Announced on X by Stripe). Stripe balance is the “agent control dashboard” where Consumers add money, set a per purchase limit, and their agent can buy without asking for approval every time. Read it. On the surface it is a wallet feature. Underneath it is Stripe building a consumer business, because right now Stripe is the only company that can make agentic payments work.

I think this is brilliant, but Issuing banks, merchants, MSPs and other agentic Platforms should take note of Stripe’s very big expansion into consumer direct interaction

What Stripe Launched

The stack has four parts

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us

Walmart Agent Gateway

This month Walmart announced Agent Profiles, the Walmart Agent Gateway and a set of terms for AI agents (Walmart, “Making It Possible for Agents to Shop on Behalf of Customers,” Oct 2026). Walmart is supporting customers the way they want to shop: through the agents they choose, with the customer’s controls and Walmart’s rules. In March I described Amazon vs Walmart: Two Very Different Bets on Agentic Commerce. This is Walmart’s bet made concrete, and IMHO it is the most important retail move in agentic commerce this year.

Walmart just became the retail partner of choice for every third party agent, and it kept the payment, the risk, the customer experience and the support.

You need to be logged in to view the rest of the content. Please . Not a Member? Join Us